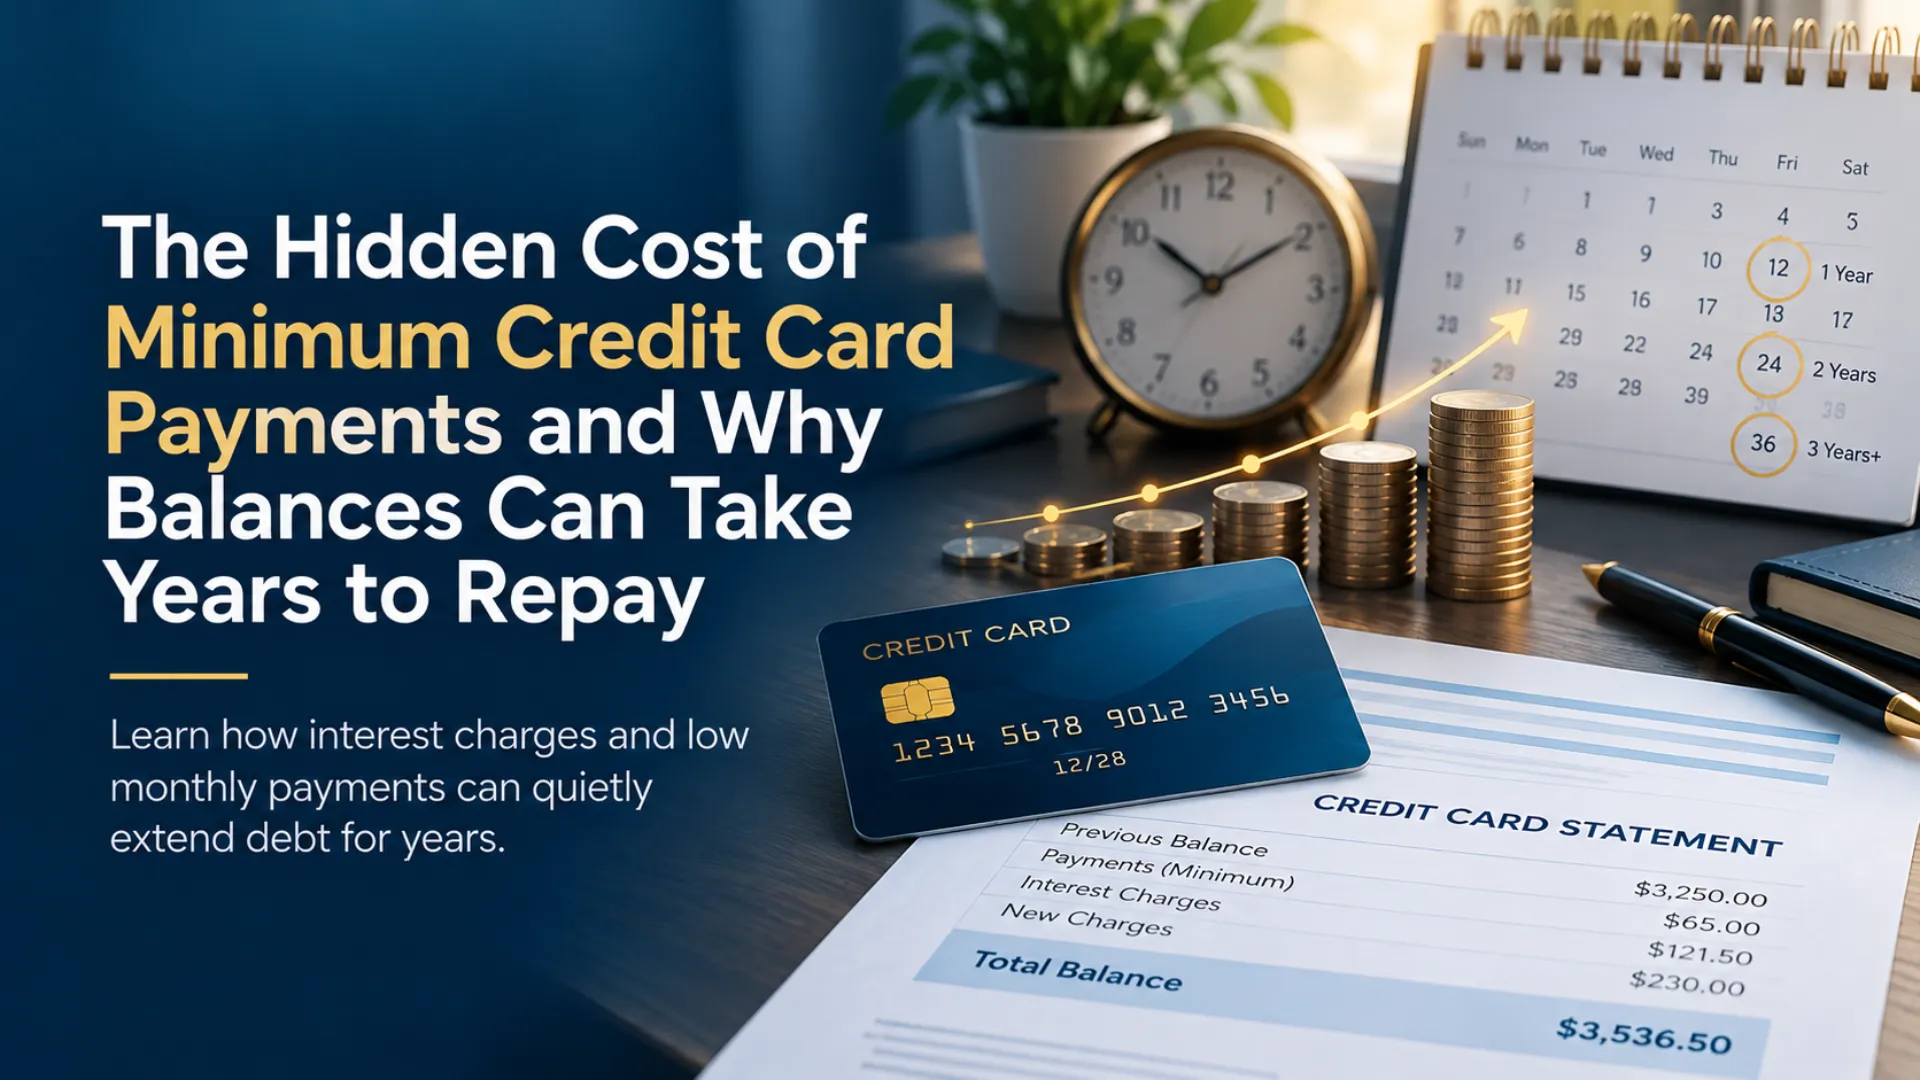
A minimum credit card payment can be convenient when money is limited, but its purpose is often misunderstood. It is generally the smallest amount a cardholder must pay by the due date to satisfy the account’s current payment requirement. It is not necessarily the amount needed to repay the outstanding balance within a short or predictable period. When a cardholder carries a balance, interest may continue accumulating while relatively little of each payment reduces the principal. A payment that keeps an account from becoming past due can therefore coexist with a balance that declines only slowly. Understanding this difference is especially important for households that regularly rely on revolving credit to manage expenses.
Credit card repayment periods are influenced by interest rates, outstanding balances, new transactions, and the amount paid each month. A borrower who consistently makes small payments may spend considerably more on interest than someone who pays additional amounts toward the same balance. Even when no new purchases are made, interest charges can consume a substantial portion of a monthly payment. The situation becomes more complicated when several accounts have different rates, billing dates, and minimum payment calculations. The total cost of borrowing is therefore not determined by the original purchase amount alone. Examining the relationship between interest and repayment behavior helps explain why certain balances remain outstanding for years.
Why Minimum Credit Card Payments Change Over Time
Credit card issuers generally calculate minimum payments according to the terms described in their cardholder agreements. Depending on the account, the required amount may be based on a percentage of the outstanding balance, a fixed minimum amount, or a combination of principal, interest, and applicable fees. As the balance changes, the minimum payment may also change from one billing cycle to another. This means the amount required today may not remain the same throughout the repayment period. Consumers who assume that the minimum payment is a fixed installment can misunderstand how long repayment will take. Unlike a traditional installment loan with a defined repayment schedule, revolving credit allows balances to change as transactions, payments, and interest charges occur.
A decreasing minimum payment can create the impression that an account is becoming easier to manage. However, paying a smaller amount each month may slow the rate at which the remaining principal declines. When minimum payments fall along with outstanding balances, the repayment process can continue much longer than expected. This pattern is particularly relevant when cardholders do not increase payments despite having additional funds available. Making only the required amount may provide short-term budget flexibility, but it can also result in higher cumulative interest expenses. Understanding the issuer’s payment calculation helps consumers distinguish between an affordable monthly obligation and an efficient repayment schedule.
How Credit Card Interest Influences the Total Amount Repaid
Credit card interest is commonly expressed as an annual percentage rate, but many issuers calculate charges using daily account balances. The daily periodic rate is generally derived from the applicable APR, although the precise calculation depends on the issuer’s terms. Because interest can accrue throughout the billing cycle, the dates of purchases and payments may influence the final interest charge. A larger revolving balance typically produces greater interest costs than a smaller balance carrying the same rate over the same period. This relationship helps explain why reducing principal can become increasingly valuable when borrowing costs are high. It also shows why borrowers should examine their actual interest charges rather than relying exclusively on the advertised APR.
For illustration, a $1,000 balance carrying a 24 percent APR could generate approximately $20 in interest over a month, depending on the number of days and the account’s calculation method. That amount represents a borrowing cost rather than repayment of the original $1,000 principal. If the cardholder makes a $30 payment and no other charges apply, only a relatively small portion may reduce the outstanding principal. The actual amounts will vary with payment timing, additional transactions, applicable fees, and the issuer’s interest calculation. When this relationship repeats over multiple billing cycles, the accumulated interest can become significant. The example demonstrates why repayment amounts should be considered in relation to both the interest rate and the remaining balance.
Understanding the Information on a Credit Card Statement
Monthly credit card statements contain information that can help borrowers evaluate the cost of maintaining an outstanding balance. Common disclosures include the previous balance, recent transactions, payments, fees, interest charges, current balance, and payment due date. Statements also identify applicable interest rates and may separate balances according to transaction categories. Under federal credit card disclosure rules, many consumer credit card statements must provide information showing the potential consequences of paying only the minimum amount. These disclosures are intended to make repayment costs easier to understand. Reviewing them regularly can reveal important differences between making a required payment and paying down the balance efficiently.
A minimum payment warning generally illustrates how repayment time and interest costs can increase when borrowers make only minimum payments. Many statements also provide an estimated monthly amount needed to repay the displayed balance within approximately three years, subject to applicable rules and assumptions. The estimates generally assume that no additional purchases are made and that relevant account conditions remain consistent. Actual repayment outcomes may differ when interest rates change or additional transactions occur. Nevertheless, the comparison can help borrowers understand the financial effect of allocating more money toward repayment. The figures are particularly useful when evaluating whether a current payment pattern is consistent with a household’s broader financial goals.
How Revolving Credit Balances Can Affect Credit Reports
Credit card balances can influence more than monthly borrowing costs because account information is also used in consumer credit reporting. Card issuers commonly report information about balances, payment activity, account status, and credit limits to credit reporting agencies. Credit scoring models consider several factors, including payment history and the amount of credit being used. The proportion of revolving credit balances relative to available credit limits is commonly called credit utilization. A high utilization level can negatively affect some credit scores, although scoring models differ in how they evaluate account information. This means that paying bills on time and maintaining low revolving balances can influence different aspects of a consumer’s credit profile.
Credit utilization should not be confused with the total amount of money a person earns or saves. It describes the relationship between reported revolving balances and available revolving credit limits rather than the overall condition of household finances. A person may have sufficient income to meet monthly obligations while still reporting high utilization on certain accounts. Conversely, a low reported balance does not by itself demonstrate that someone has adequate savings or manageable living expenses. Credit scores are based on information in credit reports and do not provide a complete assessment of financial well-being. Evaluating credit card use alongside income, expenses, emergency savings, and other obligations gives a more meaningful picture of financial stability.
Repayment Habits That Can Reduce Long-Term Borrowing Costs
Consistently paying more than the minimum amount can reduce the time needed to repay a revolving credit card balance. Additional payments generally help lower outstanding principal, which can reduce future interest charges when the balance is subject to interest. The benefit depends on the account’s interest rate, payment allocation rules, and whether the borrower continues making new purchases. For people with multiple credit cards, directing additional payments toward higher-interest balances may reduce total borrowing costs under otherwise comparable conditions. Avoiding unnecessary new charges during repayment can also prevent outstanding balances from increasing again. These practices are most effective when payment amounts remain realistic within the household budget.
Payment timing is another consideration because many credit card issuers calculate interest using daily balances. When an account is accruing interest, making a payment earlier can sometimes reduce the amount of interest charged compared with paying the same amount later. However, borrowers must still ensure that the required payment is received by the contractual due date. Automatic payments may help maintain consistency, provided sufficient money is available in the linked bank account. Reviewing payment confirmations and monthly statements is important because processing delays or insufficient funds can create unexpected problems. A stable repayment routine combines timely payments, careful expense monitoring, and adjustments when financial conditions change.
Recognizing When Minimum Payments Are No Longer Affordable
Difficulty making minimum payments can indicate that a household’s current financial obligations exceed the amount available after essential expenses. This problem may develop gradually through increased borrowing or suddenly following job loss, illness, or another financial disruption. Repeatedly relying on additional credit to cover existing payment obligations can increase overall indebtedness. When required payments become unaffordable, ignoring the situation may lead to additional fees, delinquency, and collection activity. The Consumer Financial Protection Bureau advises consumers experiencing payment difficulties to contact their credit card companies as soon as possible. Early communication may allow borrowers to discuss available payment arrangements before account problems become more serious.
Financial difficulties do not always require the same response because account terms and household circumstances vary. Some borrowers may be able to address temporary cash shortages through revised budgets or arrangements with creditors. Others may need help understanding their obligations through reputable credit counseling or appropriately qualified financial professionals. Any proposed repayment arrangement should be evaluated according to its total cost, duration, fees, and possible effect on existing accounts. Borrowers should also be cautious about promises that debt can be eliminated quickly or reduced by a guaranteed percentage. Recognizing repayment problems early and understanding the actual terms of available options can support more informed decisions about managing outstanding credit card balances.